
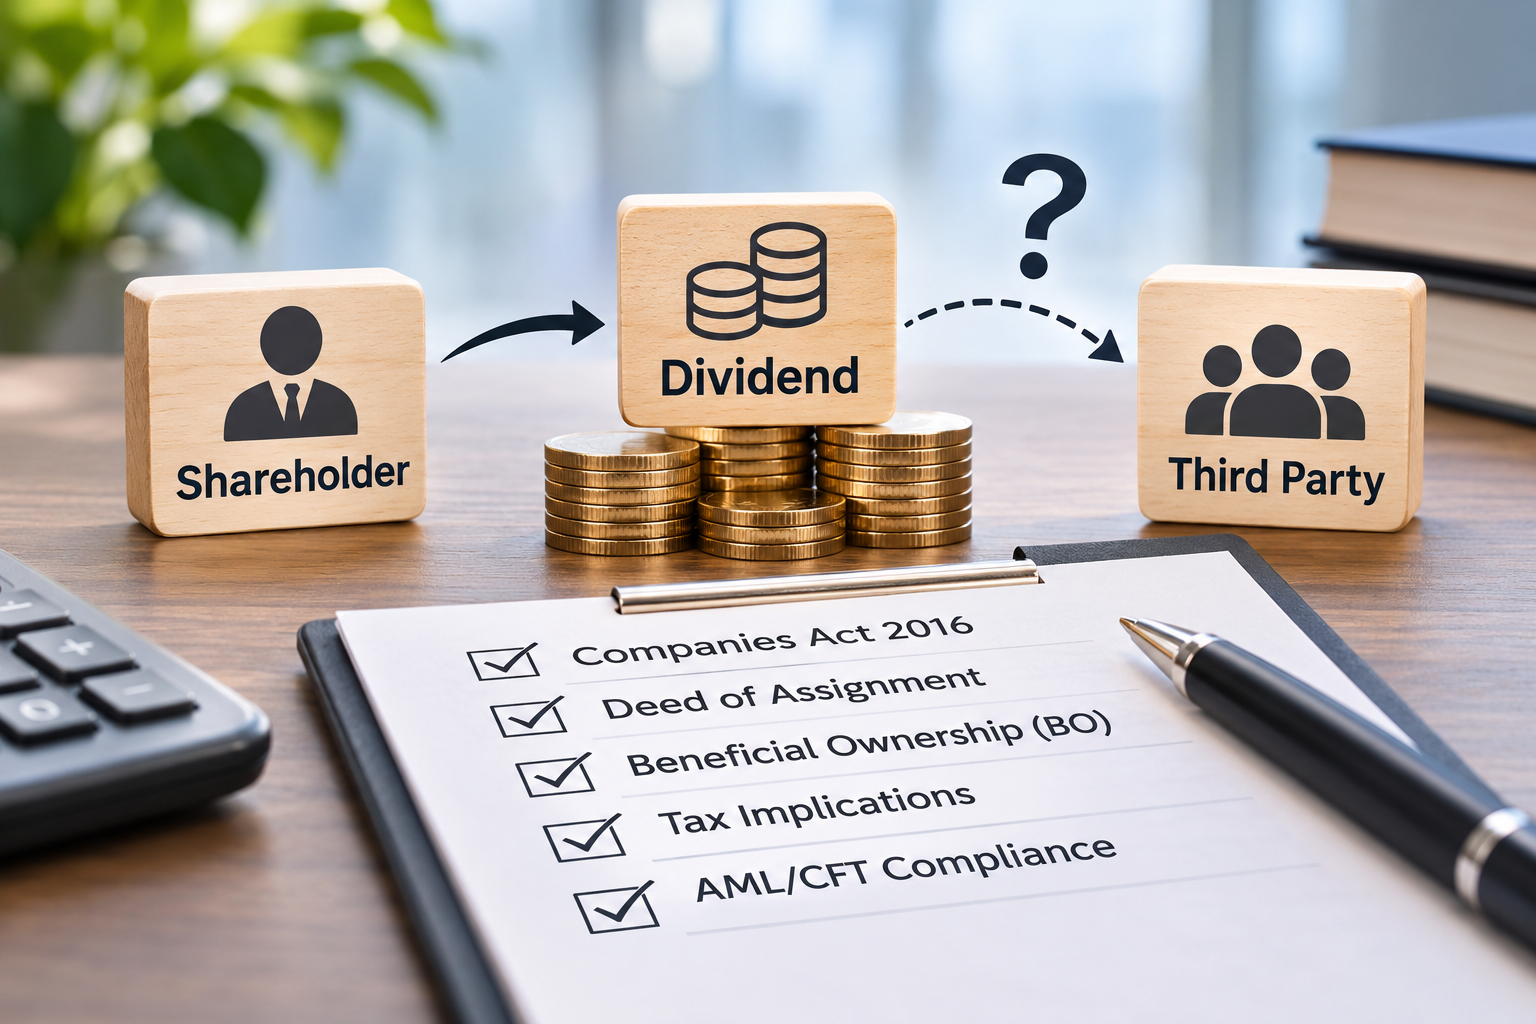
Can a Company Pay Dividends to Someone Other Than Its Shareholder?
Understanding the legal, tax and compliance implications of third-party dividend payments, Deeds of Assignment, beneficial ownership and AML/CFT considerations under Malaysian law.
1. A Simple Payment Request That May Create Complications
Imagine a Malaysian company has declared a dividend to its shareholder. However, instead of receiving the dividend directly, the shareholder requests the company to pay the money to someone else.
There could be various reasons behind such a request:
- The shareholder does not have a personal bank account in Malaysia.
- The shareholder wants the dividend paid to a family member or spouse.
- The shareholder has an outstanding debt and wishes the dividend to be paid directly to a creditor.
- The shareholder wants the dividend transferred to another shareholder or business associate.
- The shareholder is facing personal banking or administrative difficulties.
- The shareholder has entered into a private arrangement with another person to receive the dividend on their behalf.
The proposed recipient may be related or unrelated to the shareholder, and may even be another shareholder of the same company.
To the company, this may appear to be a simple payment instruction. The shareholder may even provide a signed letter authorising the company to make the transfer.
But should the company simply follow the instruction?
Not necessarily.
A dividend payment is not merely a matter of transferring money to a nominated bank account. The company must consider whether the payment is legally valid, whether its obligation to the shareholder will be discharged, and whether the arrangement creates additional corporate, beneficial ownership, tax or AML/CFT compliance risks.
2. What Does the Companies Act 2016 Say?
Under Section 131 of the Companies Act 2016, a company may only make a distribution to its shareholders out of profits available for distribution, provided that the company satisfies the solvency test.
Section 132 further requires the distribution to be authorised by the directors. The directors must be satisfied that the company will remain solvent immediately after the distribution.
These provisions establish the statutory requirements for making dividend distributions.
However, the Companies Act 2016 does not expressly set out a procedure for paying a shareholder’s dividend entitlement into an unrelated third party’s bank account.
This does not automatically mean that every third-party payment is prohibited. Nevertheless, the absence of an express procedure should not be interpreted as automatic permission to make such payments.
The company should establish a proper legal basis before considering any arrangement that departs from the normal payment practice.
3. Is a Letter of Authorisation Sufficient?
A shareholder may sign a letter instructing the company to pay the dividend to another person.
However, there is an important distinction between:
- Authorising a payment: The shareholder instructs the company to transfer money to a nominated bank account.
- Assigning a legal entitlement: The shareholder transfers the legal right to receive the dividend to another person.
These are not necessarily the same arrangement.
A letter of authorisation may record the shareholder’s payment instruction, but it does not automatically establish that the recipient has become legally entitled to the dividend.
The company should also consider what happens if the original shareholder subsequently disputes the payment or claims that the dividend remains unpaid.
The key question is:
Will payment to the nominated third party fully discharge the company’s obligation to the original shareholder?
If this cannot be established with sufficient legal certainty, the company should not simply proceed based on the shareholder’s instruction.
4. What About a Deed of Assignment?
A shareholder may argue that a Deed of Assignment can be used to transfer their dividend entitlement to another person.
However, does signing a Deed of Assignment automatically allow the company to pay dividends to that third party?
Not necessarily.
Section 4(3) of the Civil Law Act 1956 provides for the assignment of certain debts and legal rights, subject to specific legal requirements.
However, the company must consider whether the dividend entitlement can be validly assigned and, more importantly, whether payment to the assignee would legally discharge the company’s obligation to the shareholder.
A Deed of Assignment is not an automatic solution to the company’s dividend payment obligations.
5. Could the Arrangement Affect Beneficial Ownership (BO)?
Another consideration is whether the arrangement has any implications for the company’s beneficial ownership information.
Under the Companies Act 2016 and the applicable SSM beneficial ownership framework, beneficial ownership generally concerns the natural person who ultimately owns or controls shares, or exercises ultimate effective control over a company.
An assignment of dividend entitlement does not automatically mean that the recipient becomes the beneficial owner of the shares.
For example, where a shareholder assigns only the right to receive a particular dividend to another person, the original shareholder may continue to hold the shares and retain the voting rights and other shareholder rights.
However, the company should not overlook circumstances suggesting that the arrangement goes beyond a simple transfer of dividend entitlement.
Further enquiries may be necessary if the recipient:
- Exercises voting rights attached to the shares;
- Has influence or control over the shareholder’s decisions;
- Holds or controls shares on behalf of another person;
- Enjoys wider economic rights or control over the shares; or
- Is involved in an arrangement that may conceal the actual beneficial owner.
If the arrangement indicates a change in the actual ownership or control of the shares, the company should reassess its beneficial ownership information and determine whether any update or notification is required.
Receiving a dividend on behalf of a shareholder does not, by itself, make the recipient the beneficial owner of the shares. However, the company should ensure that the arrangement is not being used to conceal the actual ownership or control of the company.
6. Tax Perspective: Does an Assignment Transfer the Dividend Income to the Recipient?
There is another important aspect that companies and shareholders should consider: the tax treatment of the dividend.
The transfer the legal right to receive a dividend payment to another person does not automatically mean that the dividend income, for income tax purposes, is transferred from the original shareholder to the assignee.
It is important to distinguish between:
- The shareholder who is legally entitled to the dividend;
- The person who receives the dividend payment; and
- The person to whom the dividend income is attributed for tax purposes.
These may not necessarily be the same person.
For example, if a shareholder assigns the right to receive a dividend to another person, the assignee may receive the money directly from the company. However, the assignment alone does not establish that the assignee becomes the person deriving the dividend income for tax purposes.
The tax treatment should be considered based on the legal and beneficial entitlement, the nature and timing of the assignment, and the applicable provisions of the Income Tax Act 1967.
This is particularly relevant following the introduction of the 2% dividend tax from YA 2025. Under the new rules, qualifying dividend income received by an individual exceeding RM100,000 annually is subject to a 2% tax on the relevant chargeable dividend income, subject to the applicable exclusions and conditions.
Accordingly, companies should not assume that paying a dividend to a third party automatically shifts the dividend income or any applicable tax implications to that recipient.
The company should also ensure that its dividend vouchers, accounting records and tax-related documentation accurately reflect the actual dividend entitlement and payment arrangement.
A Deed of Assignment may deal with the legal entitlement to receive the money, but it should not be treated as a tax-planning instrument that automatically transfers the income or tax responsibility to another person.
Where the arrangement involves a transfer of dividend entitlement, the parties should obtain appropriate tax advice before proceeding.
7. What About AML/CFT Compliance?
Third-party dividend payments may also raise Anti-Money Laundering and Counter Financing of Terrorism (AML/CFT) considerations.
A payment to an unrelated third party is not automatically suspicious or unlawful. Nevertheless, where the company secretary is subject to AML/CFT obligations as a reporting institution, the arrangement should be assessed using a risk-based approach.
Relevant considerations may include:
- Who is the proposed recipient?
- What is the relationship between the shareholder and the recipient?
- Why is the dividend being paid to this particular person?
- Is the recipient the actual owner of the nominated bank account?
- Will the recipient retain the dividend or transfer it to another person?
- Is there any connection with a politically exposed person (PEP), sanctions risk or other relevant risk indicators?
The company secretary should conduct appropriate customer due diligence and retain supporting documents in accordance with the applicable AML/CFT requirements.
If the circumstances give rise to suspicion or reasonable grounds for suspicion, the relevant reporting obligations should be considered.
Importantly, having a Deed of Assignment, board resolution or letter of indemnity does not automatically eliminate AML/CFT risks. Legal documentation and AML/CFT assessment serve different purposes.
8. Should a Company Agree to Pay Dividends to a Third Party?
From a corporate governance and compliance perspective, a company should exercise caution before agreeing to pay dividends to someone other than the shareholder legally entitled to receive them.
A shareholder’s request or written instruction does not automatically remove the company’s legal obligations or potential exposure.
Before considering such an arrangement, the company would need to assess:
- Whether there is a valid legal basis for making payment to the third party.
- Whether the arrangement effectively discharges the company’s obligation to pay the shareholder.
- Whether the necessary legal documentation and notices are in place.
- Whether there are any tax implications arising from the arrangement.
- Whether the arrangement raises beneficial ownership or AML/CFT concerns.
These considerations may create additional work, professional costs and compliance responsibilities for the company and its directors.
The company secretary should also exercise independent professional judgement rather than simply processing every payment instruction received from a shareholder.
Where the legal position is uncertain, the company should seek independent legal advice. If the legal basis cannot be established or the associated risks cannot be adequately addressed, the company should decline the request and require payment to be made directly to the shareholder legally entitled to receive the dividend.
A company is not expected to accommodate every unusual payment instruction. Protecting the company’s interests and ensuring compliance should remain the priority.
9. Conclusion: Compliance Is More Than Following Instructions
A request to pay dividends to someone other than the registered shareholder may appear simple, but it can involve several important considerations:
- Companies Act 2016 requirements;
- The legal validity of an assignment;
- Whether the company’s payment obligation is discharged;
- Beneficial ownership transparency;
- Income tax implications; and
- AML/CFT compliance.
It would be too broad to conclude that every third-party dividend payment is prohibited by law. Equally, it would be unwise to assume that a shareholder’s written instruction is sufficient authority for the company to proceed.
The appropriate approach is to assess the circumstances, establish a legally supportable basis and ensure that the company’s statutory and compliance obligations are properly addressed.
At CLPC Advisors, we believe that corporate compliance is not simply about processing documents or following instructions. It is about exercising professional judgement, identifying potential risks and protecting the interests of the company.
10. Practical Recommendation: Pay Dividends Directly to the Entitled Shareholder
The recommended approach is straightforward: follow the normal dividend distribution process under the Companies Act 2016 and pay dividends directly to the shareholders legally entitled to receive them, in accordance with the Company’s Register of Members, applicable share rights and relevant entitlement date.
This is generally the more straightforward approach and helps avoid unnecessary legal uncertainty, additional documentation, potential tax complications and AML/CFT concerns arising from third-party payment arrangements.
Where there is no compelling reason to depart from the normal process, companies should avoid introducing alternative payment arrangements.
Our recommendation is simple: Follow the normal statutory dividend payment route. Pay dividends directly to the shareholders legally entitled to receive them.
About CLPC Advisors
CLPC Advisors provides accounting, taxation, corporate secretarial and business advisory services to businesses in Malaysia. We help business owners understand their financial position, meet compliance requirements and make informed decisions to support sustainable growth.
For professional assistance with your business’s financial planning, tax considerations or corporate advisory & corpotate Governance needs, visit CLPC Advisors.
Prepared & Reviewed By
Pang Cheng Leong (CL Pang ) is the Managing Director of CLPC Advisors Sdn Bhd, a professional services firm in Malaysia providing corporate tax, accounting, corporate secretarial and business advisory services.
He is a Chartered Accountant in Malaysia, Chartered Tax Practitioner, Licensed Income Tax Agent under Section 153 Income Tax Act Malaysia and Licensed Company Secretary, and has extensive experience advising Malaysian companies, startups and foreign investors on taxation, compliance and business structuring.
Professional affiliations: CA (Malaysia), CPA (Australia), CPA (Malaysia), ASEAN CPA, ACTIM
Disclaimer:
This article is intended for general information and educational purposes only. It does not constitute legal or tax advice. The legal, tax and compliance implications of any dividend payment arrangement should be assessed based on its specific circumstances.